Market Overview: Defining the Building and Construction Glass Market
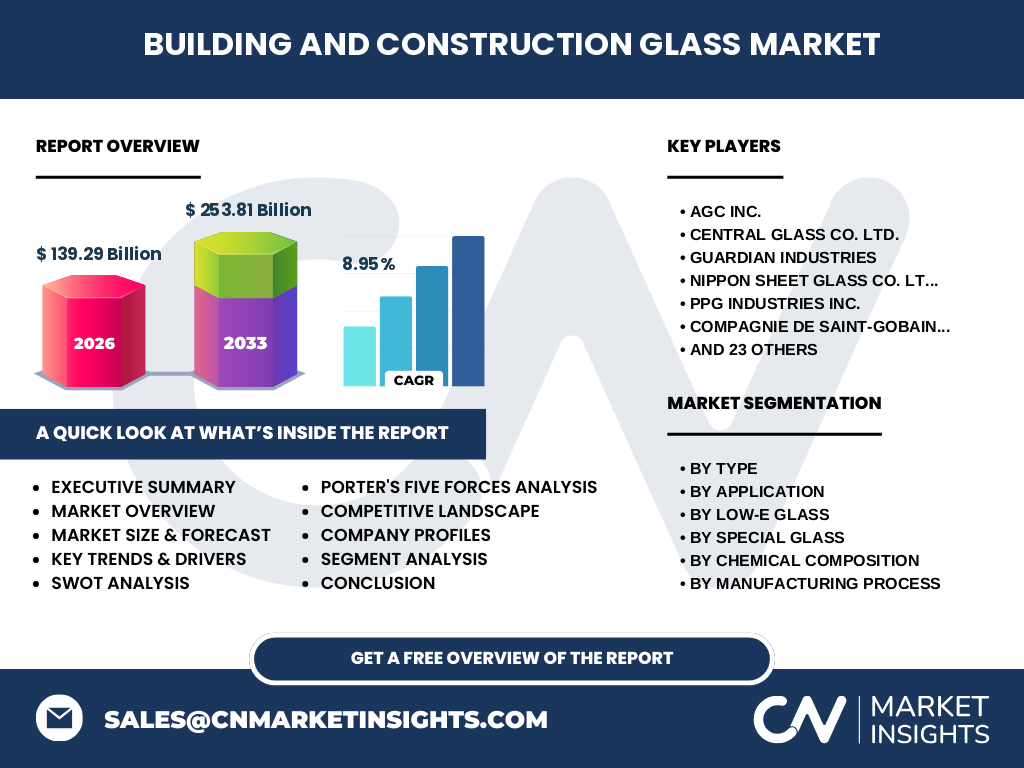
The Building and Construction Glass Market serves as the backbone of modern architectural design. Valued at 139.29 Billion in 2026, this sector encompasses a broad spectrum of glass types—from structural Low-E glass to advanced Special glass—essential for energy efficiency and structural integrity in both residential and non-residential envelopes. It is a critical component of sustainable urbanization, directly influencing global carbon footprints through thermal performance and light transmission capabilities.
Structural Growth Drivers and Market Constraints
Primary drivers include stringent energy-efficiency mandates and the rising demand for high-performance facades. While the market faces logistical hurdles in raw material supply chains for Soda-Lime and Potash-Lime, the 8.95% CAGR reflects robust demand. Regulatory bodies like the International Energy Agency push for greener glazing, yet market expansion remains constrained by high capital expenditure for Float Glass production lines and localized trade barriers in key manufacturing hubs.
Emerging Trends Shaping Industry Evolution
The shift toward high-performance thermal insulation is defining the current landscape. We observe a move away from traditional glazing toward Triple-Glazed Low-E glass to meet aggressive carbon neutrality goals. Technology innovators are increasingly integrating smart functionalities into Special glass categories, such as self-cleaning and acoustic-dampening coatings. These advancements, coupled with rapid digitalization in manufacturing, are significantly optimizing supply chain efficiency and product life cycles.
COVID-19 Impact and Recovery Trajectory
The pandemic caused severe supply chain disruptions and a temporary contraction in non-residential construction projects. However, our analysis shows a sharp post-pandemic rebound as governments prioritized green infrastructure spending. The recovery trajectory is supported by a shift toward safer, tempered, and laminated safety glass in public spaces, ensuring that the Building and Construction Glass Market remains resilient, steadily climbing toward its projected 253.81 Billion market valuation by 2033.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains high, dominated by titans like AGC Inc., Compagnie de Saint-Gobain S.A., and Guardian Industries. Strategic dynamics center on vertical integration and geographical reach. Smaller, localized players like Guangzhou Topo Glass Co. Ltd. and Asahi India Glass Limited are successfully competing by leveraging niche expertise in fire-resistant and acoustic glass. This fragmentation creates a competitive environment where R&D investment is the primary differentiator for long-term market leadership.
Executive Summary: Key Findings of the Building and Construction Glass Market Report
Our comprehensive report reveals a robust outlook, with the market growing from 139.29 Billion in 2026 to a staggering 253.81 Billion by 2033. This 8.95% CAGR is fueled by urbanization in APAC and stringent green building codes in Europe. Major players are pivoting toward Soft Coat Low-E Glass to capture value in the high-growth non-residential sector, marking a fundamental strategic shift in global manufacturing priorities.
Market Forecast: Growth Trajectory from 2027 to 2033
Based on current macro-economic indicators, the market is poised for an accelerated expansion phase. We project the Building and Construction Glass Market will reach 253.81 Billion by 2033. This trajectory assumes consistent industrialization rates in emerging economies and the global mandate for energy-efficient infrastructure. Sustained investment in Float Glass process innovation will be the primary engine driving this growth across both established and developing regional markets.
Segmentation Analysis: Categorizing the Market Landscape
The market is segmented by Type (Low-E and Special glass), Application (Residential and Non-Residential), and Manufacturing (Float vs. Rolled). Low-E glass dominates due to thermal efficiency mandates, while the Special Glass segment—including laminated and tinted options—is essential for specialized architectural security. Non-Residential applications currently capture the largest market share, driven by large-scale commercial real estate developments that require complex, high-performance glazing solutions for optimal light and energy management.
Geographic Performance: Regional Market Analysis
Geographic distribution is heavily influenced by construction intensity. APAC remains the dominant region, driven by the massive scale of infrastructure projects in China and India, involving players like KIBING Group and Fuso Glass India Pvt. Ltd. North America and Europe show high penetration for advanced Low-E technologies, with Guardian Industries and Schott AG maintaining strong footprints. Regional performance is intrinsically linked to local building code maturity and private investment levels.
In-depth Regional Review: Market Distribution
Our research indicates that the European market prioritizes sustainability, shifting rapidly toward triple-glazing. In contrast, the Middle East and Africa are scaling demand for tinted and insulated glass to manage high solar heat gain. Meanwhile, China Glass Holdings Ltd. and the Jinjing Group maintain aggressive export-oriented strategies, effectively utilizing regional logistics hubs to maintain supply chain dominance in the massive Asian construction glass ecosystem.
Company Profiles: Strategic Positioning of Industry Leaders
Industry leaders like Vitro, S.A.B. de C.V. and Oldcastle BuildingEnvelope leverage scale and innovation to command premium pricing. Şişecam exhibits a balanced portfolio, excelling in both aesthetic and functional glass types. These companies strategically manage production through Float Glass plants while diversifying into value-added laminated and acoustic glass to mitigate cyclical risks in the construction sector, ensuring sustained revenue streams despite volatile raw material costs for silica and soda ash.
Porter's Five Forces Analysis: Competitive Forces Assessment
The industry faces moderate threat from new entrants due to high capital entry barriers in the float glass process. However, the bargaining power of buyers is rising as architects demand highly customized, sustainable, and low-emissivity solutions. The competitive rivalry is intense among established incumbents like NSG Group and Saint-Gobain, forcing a continuous cycle of innovation and cost-optimization across the entire global supply chain.
SWOT Analysis: Strategic Outlook
Strengths: Established manufacturing infrastructure and robust global distribution. Weaknesses: Sensitivity to raw material price volatility. Opportunities: The rapid rise of smart glass technologies and net-zero infrastructure mandates. Threats: Increasing regulatory compliance costs and potential supply chain disruptions at major ports. Our analysis suggests that companies focusing on high-value, specialized segments like fire-resistant and acoustic glass are best positioned to neutralize these threats and capitalize on market expansion.
Value Chain Analysis: Flow from Raw Materials to End-Users
The value chain originates with the extraction of raw materials such as silica sand and soda ash. These are processed via Float or Rolled methods into raw glass sheets. Value-added processes, such as laminating or Low-E coating, significantly enhance the product margin. The final phase involves distribution to B2B construction firms, where products like those from Cardinal Glass Industries Inc. are integrated into high-performance windows and structural envelopes.
Investment Insights: Strategic Recommendations
Investors should target manufacturers specializing in Triple-Glazed Low-E Glass and advanced safety solutions. With the market projected to reach 253.81 Billion by 2033, the Non-Residential segment offers the most stable long-term yields. We recommend prioritizing companies that demonstrate high R&D spending and those successfully integrating sustainable production techniques, as these entities are best prepared to capture the growing market share in energy-efficient urban development projects.
Conclusion and Key Takeaways
The Building and Construction Glass Market is entering a high-growth phase characterized by a shift toward energy-efficient, high-performance glass technologies. The transition from 139.29 Billion to 253.81 Billion underscores the industry's role in global sustainability. Key takeaways emphasize the importance of technological innovation in the Low-E segment and the critical need for global players to optimize supply chains against regional volatility and increasing regulatory scrutiny.
Research Methodology: How Baseline Estimates are Triangulated
Our methodology employs a multi-layered approach, combining official trade registry data with primary stakeholder interviews from senior executives at firms like AGC Inc. and NSG Group. We synthesize this with macroeconomic indicators and building permit volume metrics. By triangulating these sources, we ensure our 8.95% CAGR forecast accounts for regional market fluctuations, technological shifts, and the specific cost pressures inherent to the global building and construction glass industry.
Scope of the Report: Coverage and Limitations
This report covers the global Building and Construction Glass Market, focusing on glass types—including Low-E, Special, and Float—across all key global regions. The analysis excludes automotive and decorative consumer glass, focusing strictly on architectural applications. Our data, projecting growth up to 2033, relies on current industrial capacity and forecasted infrastructure investments, noting that potential geopolitical trade policy shifts may influence specific regional growth outcomes.
Recent Developments: Strategic Moves and Market News
Recent industry activity highlights a surge in strategic partnerships and M&A, particularly as players like Fuyaogroup.com and Beijing Northglass Technologies Co. Ltd. expand their global footprints. We observe an increase in product launches focusing on smart, dynamic glazing systems. These announcements, combined with new production facility inaugurations in developing regions, signal a clear trend of capital reinvestment into advanced manufacturing processes designed to meet the growing demand for energy-efficient building materials.